
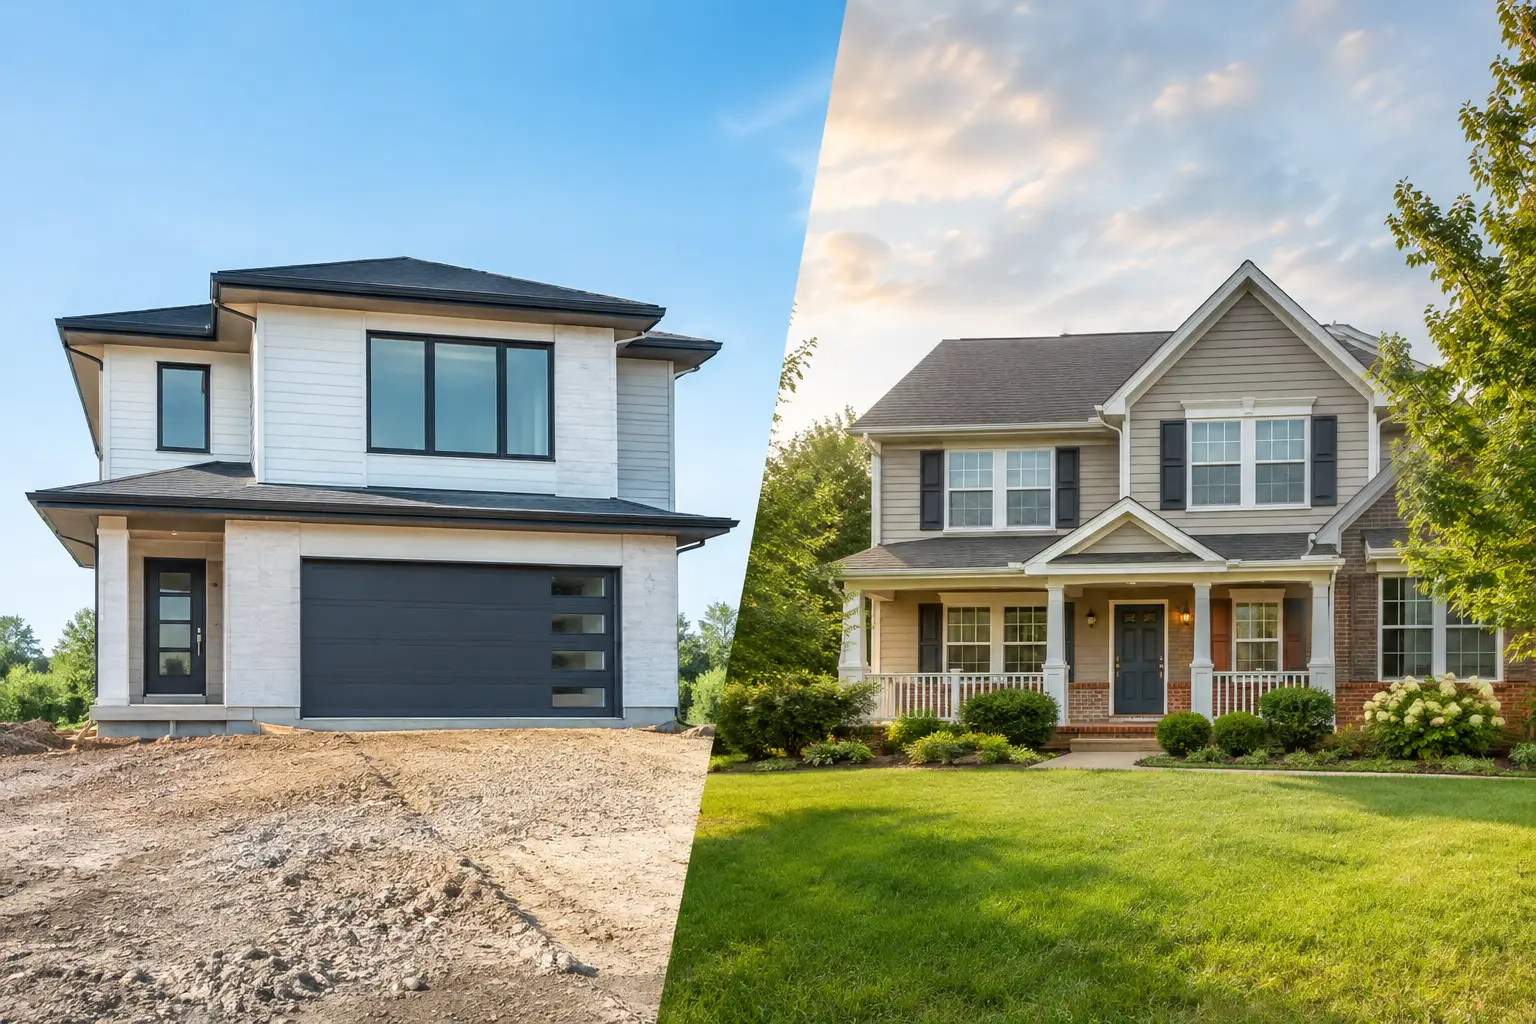
A glossy display suite can make a new build feel like the obvious choice. An established home with a mature garden, larger block and a proven street appeal can be just as compelling. The new build versus established home decision is not about choosing the newer or prettier option. It is about selecting the property that best supports your financial goals, lifestyle and risk tolerance.
For buyers across Queensland and Victoria, the right answer often comes down to the specific suburb, the quality of the dwelling, the land component and what you need the property to achieve over the next five to 10 years.
New Build Versus Established Home: Start With Your Goal
An owner-occupier buying their long-term family home may prioritise layout, energy efficiency and low-maintenance living. An investor focused on capital growth may place more weight on land scarcity, established infrastructure, tenant demand and the capacity to add value.
This distinction matters because a property can be an excellent new home without being the strongest investment acquisition, and vice versa. Before inspecting anything, be clear on your non-negotiables: budget, preferred locations, holding period, borrowing capacity, expected rental return and the role this purchase plays in your broader wealth strategy.
A new build can offer certainty around condition and functionality. An established home can offer evidence - of the street, the neighbourhood, buyer demand and the way the property has performed through different market conditions. Neither is automatically superior. The value lies in matching the asset to the strategy.
The Case for Buying a New Build
New builds appeal for good reason. They are usually designed around modern living, with open-plan spaces, contemporary kitchens, better insulation, efficient appliances and lower immediate maintenance requirements. For time-poor professionals and families, the appeal of moving into a clean, functional home without a renovation list can be significant.
From an investment perspective, newer properties may also offer stronger depreciation opportunities than older dwellings. This can improve cash flow in the early years of ownership, although the benefit should be assessed alongside the purchase price, rental income and your accountant’s advice.
A new dwelling may attract tenants seeking modern finishes, air conditioning, storage and low-maintenance outdoor areas. In growth corridors where population expansion, employment access and infrastructure are strengthening demand, a well-positioned new home can be a practical addition to a portfolio.
There are also potential government incentives for eligible first-home buyers, although these vary by state, purchase price, property type and buyer circumstances. Incentives should never be the sole reason to buy. They can help the numbers, but they do not turn an oversupplied location or an over-priced property into a sound long-term decision.
Where New Builds Need Extra Scrutiny
The biggest mistake is treating “new” as shorthand for “good buying”. New estates can carry a premium for convenience, marketing and turnkey presentation. If a large volume of similar homes and land releases are still available nearby, future buyers and tenants may have plenty of alternatives. That can limit scarcity and place pressure on resale growth.
Land size is another consideration. Many new homes are built on smaller lots, which may suit low-maintenance living but can reduce flexibility for extensions, outdoor living or future value-add projects. The building can depreciate. The land, location and scarcity are often what drive long-term capital growth.
Build quality also requires careful assessment. A new property should have appropriate inspections and contract review, particularly where construction is incomplete or recently finished. Cosmetic presentation can hide workmanship issues, drainage concerns, inadequate site preparation or finishes that do not meet expectations.
For off-the-plan purchases, buyers need to understand settlement timing, valuation risk and the contract conditions. Markets can change between signing and completion. If the valuation comes in below the contract price, you may need additional funds to settle.
Why Established Homes Remain Powerful Assets
Established homes often sit in neighbourhoods with the features buyers value most over time: mature trees, wider streets, established schools, transport links, shops, parks and a stronger sense of community. In many inner and middle-ring locations across Brisbane, Melbourne and key regional centres, these attributes are difficult to replicate in a new estate.
The core advantage is often land. An older home on a well-located block may provide more space, better street presence and future options to renovate, extend, rebuild or improve the site, subject to planning controls. This can create a more active path to equity growth than simply waiting for the market to do the work.
Established properties also allow buyers to see exactly what they are purchasing. You can inspect the natural light, assess traffic noise at different times, speak with neighbours, review the streetscape and observe how the area functions day to day. For interstate buyers, this on-the-ground assessment is especially valuable because suburb-level data only tells part of the story.
An established home may have a clearer record of local sales and rental performance as well. Comparable evidence helps buyers make a more disciplined offer, rather than relying on developer pricing or projected future value.
The Trade-Offs of Older Property
Older homes can demand more attention and a larger contingency fund. Roof condition, plumbing, wiring, drainage, pest activity, asbestos, structural movement and outdated layouts can all affect the true cost of ownership. A building and pest inspection is essential, but it is not a substitute for understanding likely future capital expenditure.
Some buyers underestimate the disruption and cost of renovation. A cosmetic update can be manageable. Moving walls, repairing structural issues or upgrading services can quickly become more expensive than expected. If you are buying an established home for its renovation potential, price the project conservatively and allow for delays.
Energy efficiency may also be lower in older dwellings. Heating, cooling and insulation upgrades may be worthwhile, but they need to be factored into your purchase decision rather than treated as an afterthought.
Compare the Total Cost, Not Just the Purchase Price
The new build versus established home comparison becomes clearer when you look beyond the advertised price. A new home may reduce immediate repair costs but carry a higher land-to-building ratio in the price. An established property may need work but offer a superior location, a larger block and stronger scarcity.
For either option, model the full position: deposit, stamp duty where applicable, legal costs, loan costs, insurance, rates, body corporate fees, expected rent, maintenance allowance and any renovation or landscaping expenses. Investors should also consider vacancy risk and the likely rentability of the home relative to nearby competition.
For owner-occupiers, think about the cost of compromise. A cheaper new build further from work, family, schools or amenities may create higher travel costs and less lifestyle flexibility. An established home in a better-connected suburb may cost more upfront but deliver stronger day-to-day value and broader future buyer demand.
Location and Scarcity Should Lead the Decision
A well-built new home in a high-demand pocket can outperform a tired established property in a weak location. Equally, an older house on scarce land near transport, employment and quality schools may have far greater long-term appeal than a brand-new dwelling in an area with years of future supply.
This is why buyers should avoid broad rules such as “always buy old” or “new builds are low risk”. The better question is whether the property has the right fundamentals for its price. Look at supply, days on market, comparable sales, demographic demand, infrastructure, flood and planning overlays, rental competition and the property’s individual condition.
A strategic purchase also considers the exit. Ask who is likely to buy or rent this property in five, 10 or 15 years. Is the appeal broad enough to support demand across different market conditions? Does the property offer something difficult to reproduce?
Make the Choice With Evidence, Not Emotion
Emotion will always play a role in property, particularly when you can picture your family living in a home. The goal is not to remove that emotion. It is to balance it with disciplined due diligence and a clear acquisition strategy.
A new build may be the right fit if you value convenience, modern design and predictable early maintenance. An established home may be the better choice if you want land, character, an established location or opportunities to add value. The strongest outcome comes from assessing the particular property, not relying on its age alone.
Property Visionaries helps buyers turn that assessment into a structured decision through suburb research, local inspections, due diligence and confident negotiation. When the numbers, location and property fundamentals align with your goals, you can move forward knowing your purchase is designed to support more than settlement day.