
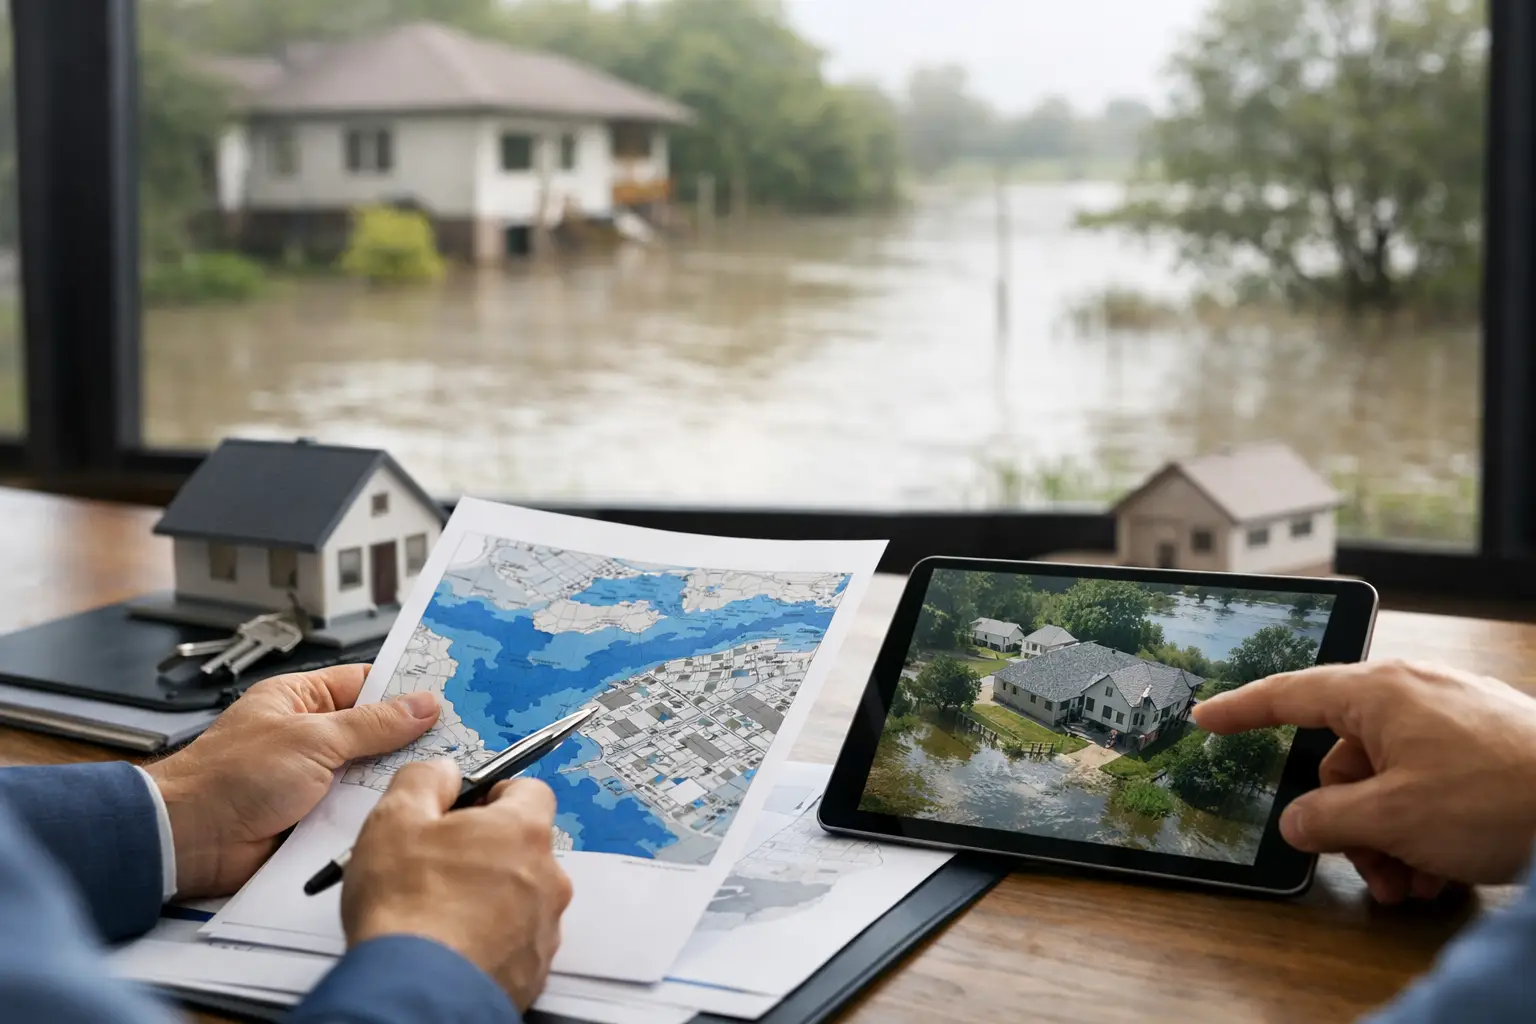
A property can look perfect at a Saturday inspection and still carry a flood exposure that affects its insurance cost, future resale appeal and your ability to sleep well when heavy rain arrives. Knowing how to assess flood risk for a property before you commit is not about automatically ruling out every home in a mapped area. It is about understanding the specific risk, the likely consequences and whether the price properly reflects them.
For buyers in Queensland and Victoria, that distinction matters. Flood mapping, planning controls, local topography and insurer appetite can vary street by street. A disciplined due diligence process turns a vague concern into a clear buying decision.
Start with the type of flood risk
Flood risk is not one thing. A home near a creek may be exposed to riverine flooding, while a property well away from a waterway may be affected by overland flow during intense rainfall. Coastal locations can face storm tide or sea-level-related inundation, and poorly drained areas may experience local drainage flooding when the stormwater network is overwhelmed.
The type of flooding determines what you need to investigate. Riverine events are often reflected in established flood studies and mapped inundation levels. Overland flow can be more localised and harder to spot, particularly where water travels down a sloping street, through easements or across backyards. A property may have avoided internal flooding in one event but still have a garage, yard, accessway or lower living area affected.
Do not rely on a vendor's broad statement that a home has never flooded. Ask more precise questions: Has water entered the dwelling, garage or undercroft? Has the property lost vehicle access? Was water close to the floor level? What happened in major local events, not just ordinary storms? The answers should then be tested against independent records.
How to assess flood risk on a property using official data
Your first objective is to establish whether the land or dwelling sits within a mapped flood-related overlay. Queensland councils commonly provide flood-check tools and flood investigation reports, while Victorian buyers can review planning scheme maps and relevant overlays. These sources are a starting point, not the final answer.
Look for designations such as flood overlay, land subject to inundation overlay, floodway, flood storage area, overland flow path or drainage constraint. The terminology differs between councils, but each can affect building works, extensions, rebuilding costs and buyer demand.
Pay close attention to what is actually mapped. Is the overlay across the rear boundary only, over a small corner of the block, through the house itself or across the sole driveway? A large block can be partly affected without making the existing dwelling high risk. Conversely, a modest mapped area may create a major issue if it crosses the access point or sits beneath a future extension area.
Also check the date and assumptions behind the mapping. Councils update flood studies as modelling improves and new rainfall data becomes available. A property outside an older map is not automatically risk-free, just as an overlay does not prove that water has entered the home. The practical question is the relationship between predicted flood levels and the finished floor level of the dwelling.
Compare flood levels with the home’s floor level
Where detailed flood information is available, ask for the defined flood level, flood planning level or applicable minimum habitable floor level. Then compare this with the surveyed or documented floor level of the house. The difference is often called freeboard - a safety margin between expected floodwater and the floor.
This comparison needs care. An advertised floor level, a rough estimate from an agent or a contour line on a map is not enough for a high-stakes decision. For properties with meaningful exposure, engage a suitably qualified surveyor, engineer or flood consultant to clarify levels and likely impacts. This is particularly valuable when you are buying interstate or considering a home on a sloping site.
A raised Queenslander may have habitable rooms safely above a predicted level but a lower garage or storage area that is vulnerable. That can be manageable if the construction, access and insurance costs are acceptable. A slab-on-ground home with its living areas close to the predicted flood level warrants a more conservative assessment.
Inspect the site, not just the house
Data tells you where water may go. A careful inspection helps explain how it could behave on the ground. Visit after rain where possible, and do not rush through the exterior because the kitchen has been renovated.
Look at the fall of the land, nearby drains, culverts, retaining walls and the direction of the street. Water naturally seeks the lowest path. A home at the bottom of a hill, beside a reserve, opposite a drainage channel or below road level deserves closer scrutiny. So does a block with a steep rear yard that appears to direct water towards the building.
Signs of past water issues can include rust or staining on fences and garage walls, warped skirting boards, repaired plaster at low levels, mouldy smells, recently replaced lower cabinetry, silt marks in sheds, or unusually high air-conditioning units and power points. None proves a flood event by itself. Together, they provide useful prompts for further investigation.
Check practical access too. If floodwater is unlikely to reach the house but regularly cuts off the road, that affects daily liveability and may influence future buyer demand. For investors, access disruptions can also affect tenant appeal and vacancy risk.
Test the insurance position before making an offer
Insurance is one of the clearest market signals available to a buyer, although it should not be your only one. Obtain quotes for building and contents insurance before you go unconditional, and disclose the full address and construction details. Ask whether flood is included, whether special excesses apply, and whether there are exclusions or limits for undercroft areas, garages and outbuildings.
Do not accept a single quote as definitive. Insurers use different models, risk tolerances and pricing approaches. Compare several providers, but take a high premium, a large flood excess or repeated quote declines seriously. These costs can change over time, and future purchasers will run the same checks.
For an investment purchase, incorporate the annual premium and excess into your cash-flow analysis. For a family home, consider the disruption as well as the financial cost. A home can be technically insurable while still being unsuitable for your lifestyle or long-term plans.
Read the contract and planning controls closely
Flood exposure can affect more than the existing building. It may limit your ability to raise, extend, build a granny flat, add a pool, create a secondary dwelling or substantially renovate after damage. Review planning controls early if value creation is part of your strategy.
Your conveyancer or solicitor should review the contract and relevant searches, while your building and pest inspector can identify visible moisture damage and drainage concerns. Their roles are different, and neither replaces specialist flood advice where mapping or property history raises questions.
If your investigation identifies material uncertainty, negotiate from evidence. That might mean seeking further information, adjusting the offer price, changing conditions where appropriate or walking away. The right outcome is not always to avoid flood-affected property. It is to avoid paying a premium price for a risk you have not properly measured.
Put the risk into the broader investment decision
A flood overlay does not cancel a suburb's growth story, and a flood-free address does not guarantee a strong purchase. Location, scarcity, land component, street appeal, nearby infrastructure and local buyer demand still matter. But flood risk changes the margin for error.
For a high-growth investment, ask whether the property will remain attractive to the next owner and tenant in a range of market conditions. A well-elevated home on a lightly affected block may outperform a cheaper but more exposed alternative over time. For an owner-occupier, the test is personal: would you be comfortable living there through a severe weather event, with the associated insurance and access risks?
At Property Visionaries, flood assessment is considered alongside suburb data, property condition, planning potential and negotiation strategy, because a confident purchase needs more than a favourable asking price. The strongest opportunities are often found by seeing both the upside and the risk with clear eyes.
A careful flood review may add time to your due diligence, but it can protect years of financial progress. Buy the property whose risk you understand, can insure and can comfortably hold - not simply the one that looked best for twenty minutes on inspection day.